Las Vegas-based financial advisor Jammie Avila has spent more than 15 years helping individuals and families throughout the Henderson, Nevada region prepare for retirement. As founder of Cornerstone Wealth Management, he builds customized retirement strategies focused on income sustainability, wealth preservation, and legacy planning, drawing on a proprietary retirement planning system he developed to simplify complex financial concepts for clients nearing retirement. Avila shares much of that approach through his book, Designed to Thrive: The Five Pillars of Retirement Planning, and through the Cornerstone Retirement Blueprint Podcast, along with the longest-running local financial news show he co-hosted on AM radio. He also serves on the board of directors of HELP of Southern Nevada. That focus on retirement income planning connects directly to a lesser-known cost many retirees face: rising Medicare premiums tied to reported income.
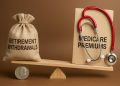
Many retirees focus on replacing a paycheck, paying bills, and covering health care costs after work slows or stops. Medicare may seem like a fixed retirement expense once someone enrolls, especially when monthly premiums look predictable.
That assumption can miss a separate rule. Changes in income reported on a federal tax return can affect Medicare Part B and Part D premiums later, so a large retirement income event may deserve review before the tax year closes.
Medicare costs include several pieces. Part B has a monthly premium, while Part D, drug coverage, usually has a plan premium that varies by plan. Here, Part B and Part D matter because both can carry income-related premium adjustments.
Social Security calls this extra charge the income-related monthly adjustment amount, or IRMAA. In plain terms, IRMAA adds to a Medicare premium when reported income exceeds certain thresholds. It can affect Medicare Part B, Medicare Part D, or both.
The adjustment does not depend only on how much money a retiree spends each month. Social Security uses federal tax return information from the IRS to decide whether the income-related amount applies. For this purpose, modified adjusted gross income, or MAGI, means adjusted gross income plus tax-exempt interest income. Tax-exempt interest is not subject to tax, but it still counts in this Medicare income measure.
Timing can make the charge feel surprising. Medicare often bases a current premium year on income from an earlier tax year, so the effect can appear after the income event has passed. A retiree who had one high-income tax year may see the Medicare cost impact later, even if current monthly income feels lower.
Moreover, the income measure can include more than wages because MAGI starts with adjusted gross income. Adjusted gross income can include wages, interest, dividends, capital gains, business income, retirement income, and other taxable income. Those sources can then affect the MAGI figure Social Security uses when it reviews income-related Medicare premiums.
Some retirement decisions can intentionally create taxable income in one year. A taxable IRA withdrawal, required minimum distribution, Roth conversion, or large taxable asset sale may increase income reported for that year. The key link is tax reporting because the action matters for Medicare premiums when it changes the income Social Security reviews. That premium effect can sit beside the tax review for the transaction itself.
The issue differs from ordinary tax planning. A retiree may already expect a withdrawal, conversion, or gain to affect taxes, but Medicare premiums can add a layer of cost. The practical question is not only whether income creates a tax bill, but whether the same transaction can also change a recurring health coverage cost.
Income can also fall after the tax year Medicare uses. A person may stop work, reduce work, experience a qualifying loss of pension income, divorce, or have a spouse die after a higher-income year. In some situations, Social Security allows people to request a new review of the income-related amount. Social Security still reviews the request before changing the amount.
Retirement income planning should compare the tax year of a large transaction with the later Medicare premium year it may affect. That timing check can show a monthly premium cost that a simple withdrawal or tax estimate may miss. The goal is not to avoid income, but to see the timing clearly.
About Jammie Avila
Jammie Avila is a financial advisor and founder of Cornerstone Wealth Management in the Las Vegas and Henderson, Nevada area, where he has helped clients with retirement and wealth planning for more than 15 years. He developed a proprietary retirement planning system, hosts the Cornerstone Retirement Blueprint Podcast, and wrote Designed to Thrive: The Five Pillars of Retirement Planning. Avila, based in Henderson, Nevada, also serves on the board of directors of HELP of Southern Nevada.